
The rate table gets all the attention. The quieter question is whether the personal loan is secured or unsecured. That single design choice changes what you risk if payments stop—and sometimes which papers the lender wants before funding.
Here is how to compare the two structures the way a careful borrower would: downside first, then cost, then convenience.
This guide is general consumer education for readers in the United States. It is not personalized financial, legal, or tax advice. Rules and product terms change by provider and state—confirm details on official pages before you apply or enroll.
Unsecured loans: profile-based installment credit
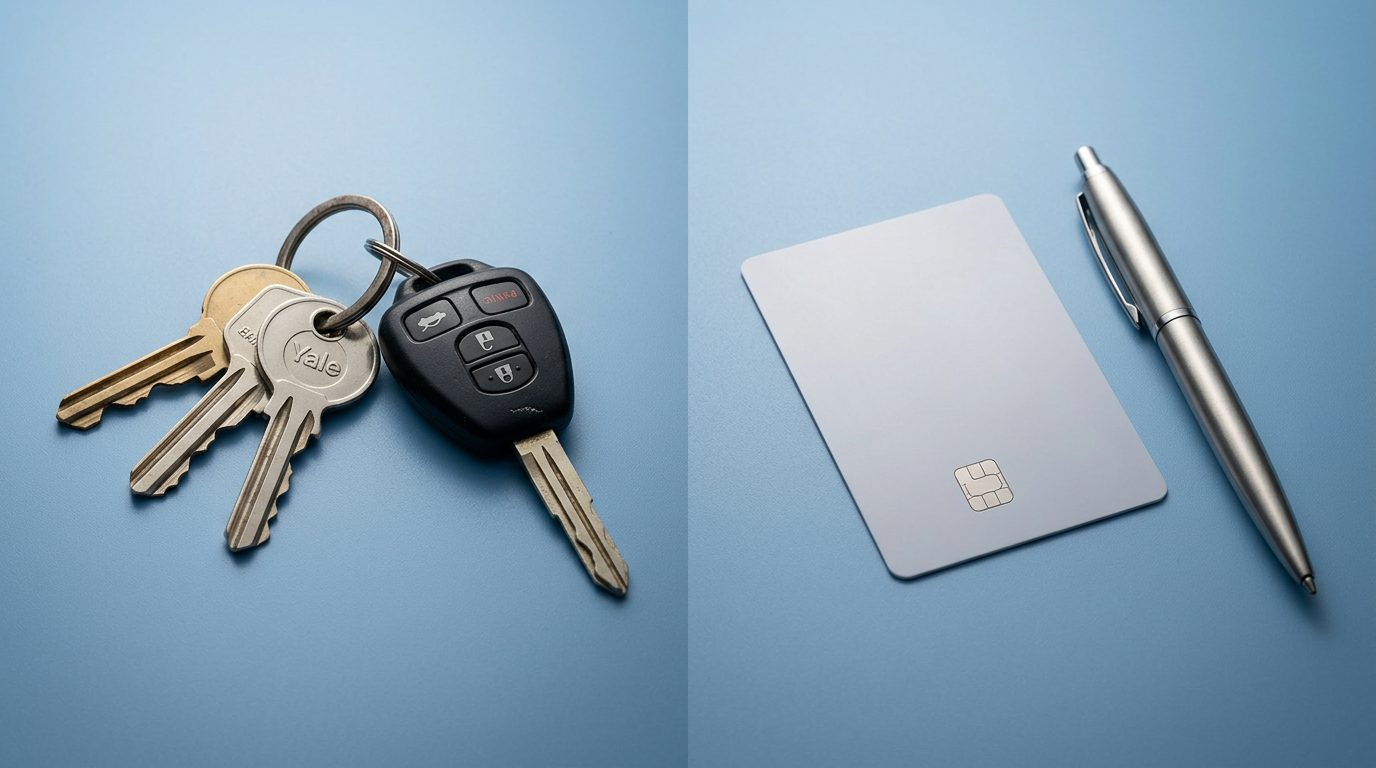
Secured vs unsecured — quick comparison
| Question | Unsecured loan | Secured loan |
|---|---|---|
| Collateral required? | Usually no | Yes — named asset |
| Main risk if you default | Collections per contract | Asset may be at risk |
| Paperwork focus | ID + income + debts | Plus ownership/deposit proofs |
| When it may fit | No pledge preference + documented income | Access needs + you accept asset risk |
| Compare either way | APR, fees, term, prepayment | Same + collateral release rules |
Unsecured personal loans generally rely on credit history, income, and existing obligations without a pledged car title or cash deposit. If you repay as agreed, the relationship ends at payoff. If you default, collection activity can still follow under the contract—but there is typically no named collateral of the secured type.
These loans are often shopped for consolidation or planned expenses. Advertised APRs may be available only to well-qualified applicants; your offer depends on underwriting.
Prefer official disclosures, agency sites, and written fee schedules over social posts or screenshots. If a claim sounds guaranteed—automatic approval, fixed savings, or risk-free outcomes—look for the conditions. Your documents, credit file, and cash flow decide real eligibility more than any headline.
Secured loans: access with an asset on the line
Secured personal loans name collateral—savings, a CD, a vehicle, or another eligible asset. That can expand access for some borrowers, including people rebuilding credit, while increasing downside risk if you default.
Before you sign, get written answers: what exact asset is pledged, how default is defined, whether deposit setoff is allowed, and how collateral is released after payoff.
Prefer official disclosures, agency sites, and written fee schedules over social posts or screenshots. If a claim sounds guaranteed—automatic approval, fixed savings, or risk-free outcomes—look for the conditions. Your documents, credit file, and cash flow decide real eligibility more than any headline.
A decision grid that stays honest
Choose unsecured when you will not pledge assets and your documented income/credit file is strong enough to shop multiple offers. Choose secured only if you understand the asset risk and still prefer that path for access or structure.
Either way, compare APR, fees, term, and prepayment rules in writing. A lower monthly payment created by a much longer term can raise total interest.
Prefer official disclosures, agency sites, and written fee schedules over social posts or screenshots. If a claim sounds guaranteed—automatic approval, fixed savings, or risk-free outcomes—look for the conditions. Your documents, credit file, and cash flow decide real eligibility more than any headline.
Behavior risks that wipe out “structure wins”
Pledging cash you may need for emergencies. Consolidating cards—then reusing them. Assuming you can refinance from secured to unsecured later without requalifying.
Prefer official disclosures, agency sites, and written fee schedules over social posts or screenshots. If a claim sounds guaranteed—automatic approval, fixed savings, or risk-free outcomes—look for the conditions. Your documents, credit file, and cash flow decide real eligibility more than any headline.
Documents and information to have ready
- Draft goal one-liner (consolidation, expense, other)
- Asset list if considering secured
- Recent credit report notes
- Income docs for whichever structure you shop
Step-by-step checklist
- Write your goal and max payment you can sustain.
- Decide whether collateral is acceptable—yes/no.
- Prequalify where soft pulls are offered.
- Compare full disclosures side by side.
- If secured, document collateral release rules before accepting.
Common mistakes and warning signs
- Signing secured terms you skimmed
- Shopping only on monthly payment
- Ignoring fees and prepayment clauses
- Hard-pulling five lenders in one day without recording why
Conclusion
Secured vs unsecured is a risk design choice. Pick the downside you can live with, then let written offers—not ads—decide the rest.
FAQ
Is secured always easier to get?
Sometimes access improves; it is not guaranteed. Lenders still underwrite income and credit.
Can collateral be my emergency fund?
Technically possible at some institutions—but tying emergency cash can backfire. Stress-test that choice.