
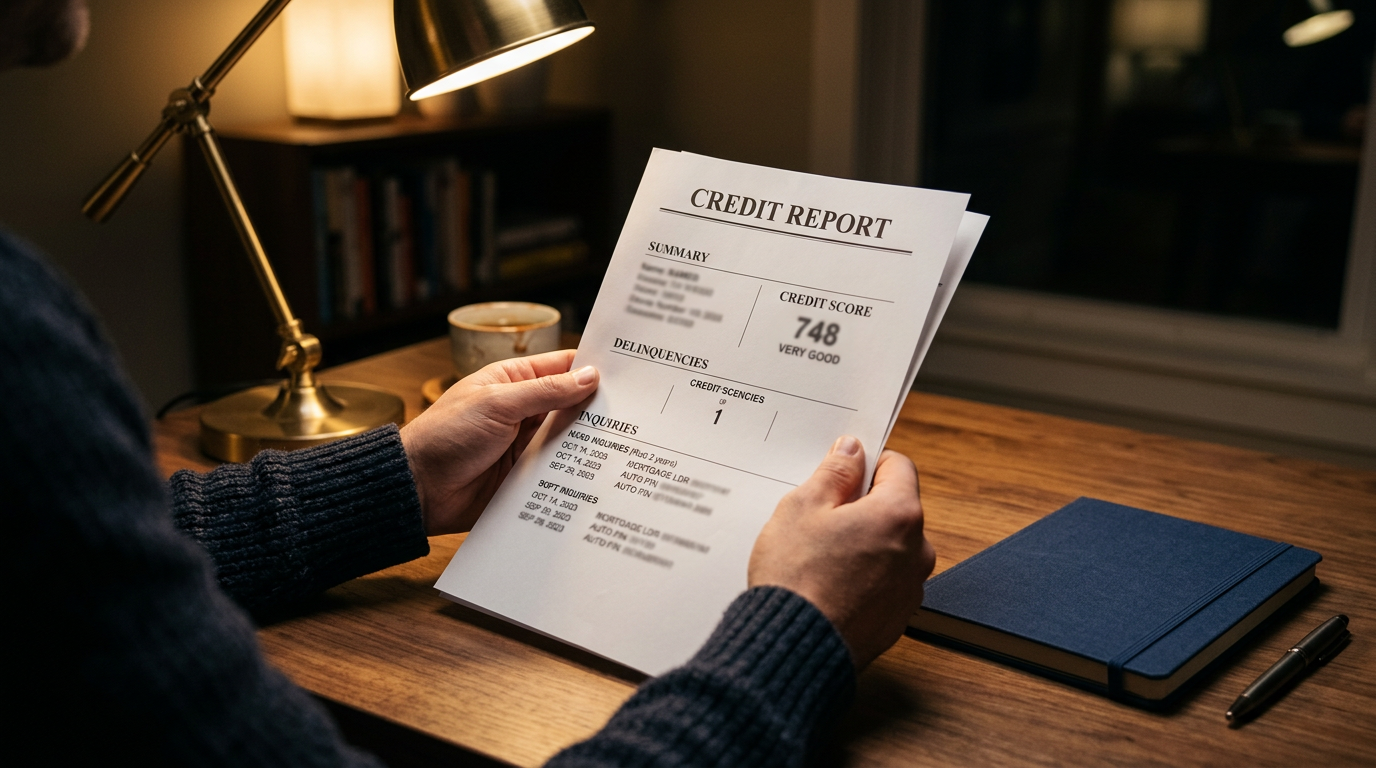
Rate shopping feels harmless until multiple hard inquiries appear on your credit report in one week. Soft pulls and hard pulls are not the same event—and lenders do not all use the same sequence.
This guide explains the difference in plain language and gives a shopping order that gathers information first, then concentrates applications when you are ready.
This guide is general consumer education for readers in the United States. It is not personalized financial, legal, or tax advice. Rules and product terms change by provider and state—confirm details on official pages before you act.
Documents and information to have ready
Before you compare offers or apply, gather photo ID, recent pay stubs or tax returns, a list of monthly debts, and any collateral details if the product is secured. Having these ready reduces mid-application stalls.
Also note your target loan amount, preferred maximum payment, and whether you need funds by a hard date. Clear constraints make weak offers easier to reject.
What soft and hard pulls usually mean
A soft inquiry often happens when you check your own credit, or when a lender prequalifies you without a full application. Soft pulls typically do not affect scoring models the way hard pulls can. A hard inquiry usually occurs when you formally apply and the lender requests your report for underwriting.
Marketing pages sometimes blur the language. Look for phrases like no impact to apply for a quote versus credit check required to continue. When unclear, ask support in writing before you submit identity details that trigger a hard pull.
Take a minute after this section to write one concrete next action on paper—something you can finish within 24 hours—so the ideas do not stay theoretical.
Why a cluster of hard pulls can matter
Scoring models may treat multiple hard inquiries for the same loan type within a short window more gently than unrelated inquiries spread over months—but that is not a free pass to apply everywhere. Extra applications still create records, and each underwriting decision can produce a denial you did not need.
Hard pulls are only one factor. Utilization, payment history, and existing balances usually dominate. Still, unnecessary inquiries are avoidable noise when you already know which offers fit.
Take a minute after this section to write one concrete next action on paper—something you can finish within 24 hours—so the ideas do not stay theoretical.
Quick reference table
| Step | Typical inquiry | Goal |
|---|---|---|
| Self check / bank soft tools | Soft | Baseline file health |
| Prequal rate range | Often soft | Shortlist without full apply |
| Full application | Often hard | Final underwriting |
| Funded loan | Account opens | New tradeline appears |
Use the table as a working checklist while you gather documents or click through settings. If a cell is blank for your situation, that is a signal to ask a clarifying question before you commit.
A safer shopping sequence
Start with your own credit reports and scores from free annual report access or your bank soft-pull tools. Fix clear errors first. Next, use lenders that advertise soft-pull prequalification and produce a rate range with estimated payments. Shortlist two or three realistic options.
Only then submit full applications—ideally within a planned window—and keep a log of dates, soft vs hard language, and outcomes. Pause if a disclosure looks worse than the prequal estimate.
Take a minute after this section to write one concrete next action on paper—something you can finish within 24 hours—so the ideas do not stay theoretical.
Document what each lender actually did
After each step, check your credit monitoring or report for new inquiries. If a process labeled soft created a hard pull, note the lender and adjust your list. Keep screenshots of prequal pages that stated inquiry type.
Take a minute after this section to write one concrete next action on paper—something you can finish within 24 hours—so the ideas do not stay theoretical.
Risks and tradeoffs to weigh explicitly
Borrowing solves a cash timing problem by creating a multi-month obligation. If income is unstable, a payment that fits today may not fit after a slow month. Prefer stress-tested payments over maximum approval amounts.
Hard inquiries, origination fees, and prepayment limits are not footnotes—they change the true cost and flexibility of the loan. Write them into your comparison before you sign.
Step-by-step checklist
- Pull your own reports and note open inquiries before shopping.
- Prefer soft-pull prequals to build a shortlist.
- Apply fully only to lenders whose disclosures match your budget.
- Cluster necessary hard pulls intentionally; do not spray applications.
- Re-check your report within a couple of days after each full apply.
Work the checklist in order when you can. Skipping ahead to the final click—apply, elect, transfer, or cancel—is how avoidable fees and denials appear.
Common mistakes and warning signs
- Assuming every check-your-rate button is soft
- Applying to six lenders the same afternoon just to see
- Ignoring a mismatch between prequal estimate and final APR
- Forgetting that a hard pull is separate from a funded loan impact
- Skipping your own report review before any lender pull
If you recognize more than one mistake already in progress, pause new commitments for a day and repair the process first.
Practical tips you can use this week
- Write soft vs hard next to each lender in your shopping log.
- Pause new applications if you have a mortgage underwriting window coming up.
- Dispute clear report errors before inviting hard pulls.
Tips are starting points. Adapt them to your budget, state rules, and the disclosures on any product you consider.
Conclusion
Information first, underwriting second. Soft discovery should narrow the field before hard pulls.
If your file is fragile, fix basics—utilization, errors, recent lates—before inviting new inquiries.
If your situation is complex—recent credit damage, mixed household finances, or specialized benefits—consider a qualified professional or reputable nonprofit counselor before you sign or enroll.
FAQ
Will one hard pull ruin my score?
Usually not by itself, but the drop can still matter before a mortgage or auto loan. Avoid stacking extras. When in doubt, prefer written plan documents and official lender or employer pages over social media summaries.
Do all lenders offer soft-pull quotes?
No. Confirm each process before sharing a full application. When in doubt, prefer written plan documents and official lender or employer pages over social media summaries.
How long do hard inquiries stay visible?
They can remain on reports for years even if scoring impact fades earlier—check your bureau display rules. When in doubt, prefer written plan documents and official lender or employer pages over social media summaries.
Is this personalized advice?
No. This is general education. Your best next step is to apply the checklists to your own numbers and confirm details with primary sources for your state and providers.