
Subscriptions grow in silence: trials that converted, annual renewals, and apps you opened twice. An hour of auditing often frees more cash than a week of coffee guilt.
Use a keep/cancel/downgrade grid so decisions are fast and reversible where possible.
This guide is general consumer education for readers in the United States. It is not personalized financial, legal, or tax advice. Rules and product terms change by provider and state—confirm details on official pages before you act.
Numbers to gather before you start
Pull two months of bank and card transactions, a list of due dates, and your essential monthly costs. Exact figures beat estimates when you redesign cash flow.
Write your income pattern clearly: fixed, variable, or mixed. The method you choose should match how money actually arrives.
Pull 90 days across every card and bank
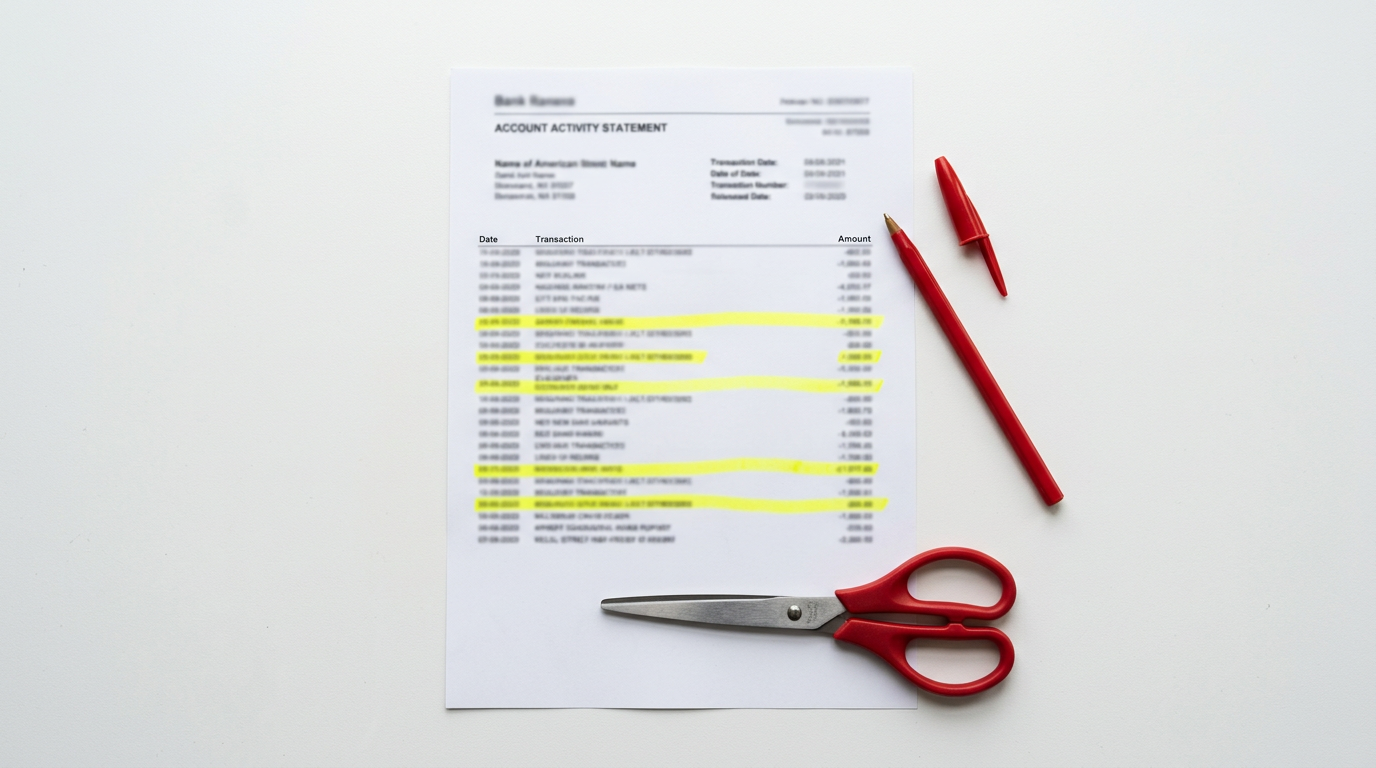
Export transactions from each debit account and credit card. Filter for identical merchants repeating monthly or yearly. Include app stores and PayPal-like wallets.
Sort by merchant name so duplicates surface even when amounts differ slightly.
Take a minute after this section to write one concrete next action on paper—something you can finish within 24 hours—so the ideas do not stay theoretical.
Score each charge in sixty seconds
Ask: Did I use this in the last 30 days? Would I buy it again today at this price? Is there a cheaper tier? Mark Keep, Cancel, or Downgrade. Do not research for ten minutes per line—park maybes in a short list.
Annual charges deserve a calendar reminder 30 days before renewal even if you keep them.
Take a minute after this section to write one concrete next action on paper—something you can finish within 24 hours—so the ideas do not stay theoretical.
Quick reference table
| Signal | Action | Follow-up |
|---|---|---|
| Unused 30+ days | Cancel | Save confirmation |
| Used but pricey | Downgrade tier | Recheck in 60 days |
| Duplicate tools | Keep one | Cancel the rest |
| Annual surprise | Calendar reminder | Decide 30 days prior |
| Trial still active | Cancel before convert | Or keep intentionally |
Use the table as a working checklist while you gather documents or click through settings. If a cell is blank for your situation, that is a signal to ask a clarifying question before you commit.
Cancel with confirmation, not hope
Cancel inside the official account settings and save confirmation emails or screenshots. Watch one more cycle for ghost charges. If a merchant makes cancellation obscure, use the card dispute path only after attempting official cancel.
Take a minute after this section to write one concrete next action on paper—something you can finish within 24 hours—so the ideas do not stay theoretical.
Prevent regrowth
Require a 48-hour wait before new subscriptions. Prefer monthly until habit is proven. Put shared household subscriptions on one owner with a shared note of logins and renewal dates.
Take a minute after this section to write one concrete next action on paper—something you can finish within 24 hours—so the ideas do not stay theoretical.
Behavioral traps that undo good systems
A beautiful budget that assumes perfect months will fail on the first surprise. Build buffers and sinking funds so the plan survives contact with reality.
Tools do not replace decisions. If automation hides duplicates or pending transactions, schedule a monthly reconciliation anyway.
Step-by-step checklist
- Export 90 days from every payment method.
- Highlight repeating merchants.
- Mark Keep / Cancel / Downgrade quickly.
- Cancel with saved confirmations.
- Set renewal reminders for annual keeps.
Work the checklist in order when you can. Skipping ahead to the final click—apply, elect, transfer, or cancel—is how avoidable fees and denials appear.
Common mistakes and warning signs
- Auditing only one credit card
- Assuming free trials auto-stop
- Sharing passwords but not renewal ownership
- Canceling a work-critical tool without checking with teammates
- Ignoring annual charges because they are not monthly
If you recognize more than one mistake already in progress, pause new commitments for a day and repair the process first.
Practical tips you can use this week
- Do the audit on the same day each quarter.
- Use browser search for manage subscription plus merchant name.
- Route new subscriptions through one card for easier future audits.
Tips are starting points. Adapt them to your budget, state rules, and the disclosures on any product you consider.
Conclusion
Subscriptions are small individually and large together. One focused hour returns cash and clarity.
Keep only what you would buy again today.
If your situation is complex—recent credit damage, mixed household finances, or specialized benefits—consider a qualified professional or reputable nonprofit counselor before you sign or enroll.
FAQ
What if I cannot find the cancel button?
Check help docs, chat support, and your app store subscriptions list. Document attempts before disputing. When in doubt, prefer written plan documents and official lender or employer pages over social media summaries.
Should I use a virtual card for trials?
It can limit exposure; still calendar the trial end date. When in doubt, prefer written plan documents and official lender or employer pages over social media summaries.
How do shared family plans fit?
Count the per-person value and decide who pays—avoid duplicate family plans across households. When in doubt, prefer written plan documents and official lender or employer pages over social media summaries.
Is this personalized advice?
No. This is general education. Your best next step is to apply the checklists to your own numbers and confirm details with primary sources for your state and providers.