
Advertised rates sell loans. Disclosures decide whether the offer is actually cheap. Origination fees, mandatory add-ons, and longer terms can make a low-APR loan cost more in dollars than a slightly higher rate with cleaner pricing.
This walkthrough shows how to line up offers side by side using the APR, fee schedule, and repayment term—so you compare finished contracts, not landing-page headlines.
This guide is general consumer education for readers in the United States. It is not personalized financial, legal, or tax advice. Rules and product terms change by provider and state—confirm details on official pages before you act.
Documents and information to have ready
Before you compare offers or apply, gather photo ID, recent pay stubs or tax returns, a list of monthly debts, and any collateral details if the product is secured. Having these ready reduces mid-application stalls.
Also note your target loan amount, preferred maximum payment, and whether you need funds by a hard date. Clear constraints make weak offers easier to reject.
Start with the written disclosure
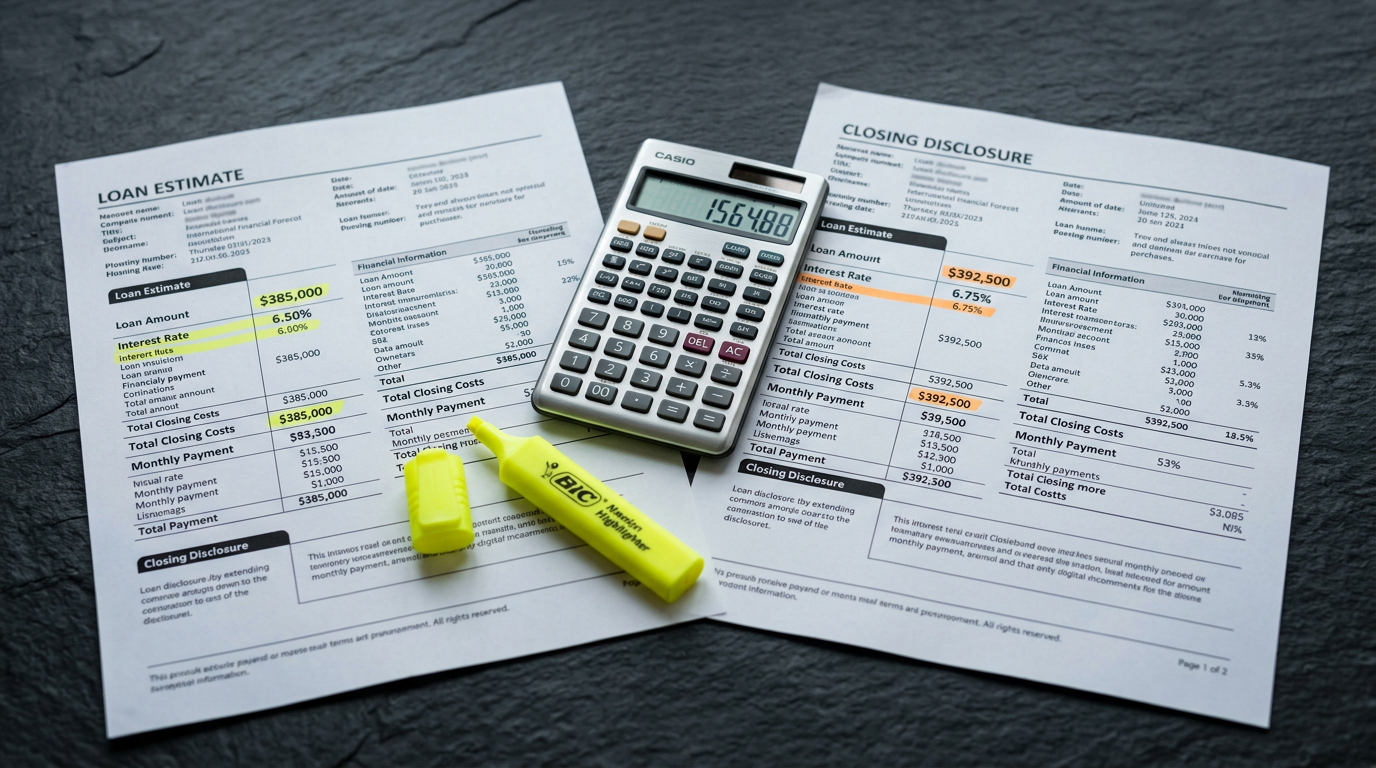
Ask every lender for a written disclosure that lists APR, finance charge, amount financed, payment schedule, and itemized fees. Marketing PDFs and chat summaries are not substitutes. If a lender will not put numbers in writing before you accept funds, treat that as a risk signal.
Confirm whether the rate is fixed or variable. Variable loans need the index, margin, and change frequency in writing. Fixed loans still need the payment and total of payments spelled out.
Take a minute after this section to write one concrete next action on paper—something you can finish within 24 hours—so the ideas do not stay theoretical.
Separate interest cost from fee cost
APR folds certain fees into an annualized rate so you can compare offers. Still read the fee list: origination deducted from proceeds, application fees, and optional products that were pre-checked. A fee taken from the loan amount means you may need a larger principal to net the cash you wanted—raising interest over the term.
Late fees, returned-payment fees, and default interest matter after funding. They do not always dominate the APR comparison, but they change what happens when cash flow slips.
Take a minute after this section to write one concrete next action on paper—something you can finish within 24 hours—so the ideas do not stay theoretical.
Quick reference table
| Item | What to capture | Why it matters |
|---|---|---|
| APR | From official disclosure | Core comparison metric |
| Origination fee | % or $ and whether deducted | Changes net proceeds |
| Term | Months and payment amount | Payment vs total interest |
| Prepayment | Allowed / penalty terms | Exit flexibility |
| Late fee | Amount and grace period | Cost of a miss |
Use the table as a working checklist while you gather documents or click through settings. If a cell is blank for your situation, that is a signal to ask a clarifying question before you commit.
Normalize term length before you crown a winner
A longer term can shrink the monthly payment while increasing total interest. Force the same loan amount and, when possible, similar terms. If terms differ, note total of payments and monthly cash-flow impact separately.
Check prepayment rules. Flexibility has value if you expect a bonus or refinance later.
Take a minute after this section to write one concrete next action on paper—something you can finish within 24 hours—so the ideas do not stay theoretical.
Build a one-page comparison log
For each offer record: net cash received, APR, monthly payment, term, origination fee, other required fees, prepayment rule, and hard-pull timing. Rank by total cost and payment fit—not by the boldest marketing number.
Take a minute after this section to write one concrete next action on paper—something you can finish within 24 hours—so the ideas do not stay theoretical.
Risks and tradeoffs to weigh explicitly
Borrowing solves a cash timing problem by creating a multi-month obligation. If income is unstable, a payment that fits today may not fit after a slow month. Prefer stress-tested payments over maximum approval amounts.
Hard inquiries, origination fees, and prepayment limits are not footnotes—they change the true cost and flexibility of the loan. Write them into your comparison before you sign.
Step-by-step checklist
- Request written disclosures from at least two lenders for the same target amount.
- Compute net proceeds after fees, not just the headline principal.
- Align terms as closely as possible before ranking total cost.
- Save PDFs of each disclosure with the date and lender name.
- Decline optional add-ons you did not request in writing.
Work the checklist in order when you can. Skipping ahead to the final click—apply, elect, transfer, or cancel—is how avoidable fees and denials appear.
Common mistakes and warning signs
- Choosing the lowest monthly payment without checking total of payments
- Ignoring fees deducted from proceeds
- Comparing a 36-month offer to a 72-month offer as if equal
- Accepting verbal rate promises without a disclosure
- Stacking hard inquiries the same day without documenting quotes
If you recognize more than one mistake already in progress, pause new commitments for a day and repair the process first.
Practical tips you can use this week
- Highlight every fee line before you compare APRs.
- Ask whether the quoted rate assumes autopay or a relationship discount.
- If net proceeds fall short, recalculate with a higher principal—or cut the project scope.
Tips are starting points. Adapt them to your budget, state rules, and the disclosures on any product you consider.
Conclusion
Treat APR as necessary but not sufficient. Pair it with fee math, term length, and payment fit.
The goal is a loan you can repay on schedule—not the flashiest rate screenshot.
If your situation is complex—recent credit damage, mixed household finances, or specialized benefits—consider a qualified professional or reputable nonprofit counselor before you sign or enroll.
FAQ
Does a lower APR always mean a cheaper loan?
Usually it helps, but fees and a longer term can erase the advantage. Compare total payments and net cash received. When in doubt, prefer written plan documents and official lender or employer pages over social media summaries.
Should I refinance just to chase a slightly lower APR?
Only if savings after fees and remaining term beat staying put—and if you will not restart revolving balances you just cleaned up. When in doubt, prefer written plan documents and official lender or employer pages over social media summaries.
What if lenders refuse a written estimate?
Shop elsewhere. Serious consumer lenders can document pricing before funding. When in doubt, prefer written plan documents and official lender or employer pages over social media summaries.
Is this personalized advice?
No. This is general education. Your best next step is to apply the checklists to your own numbers and confirm details with primary sources for your state and providers.